STRATEGIC CONSULTING
When the Decision Can Change the Company.
Independent strategic counsel for CEOs, founders, owners and boards making consequential business and capital decisions.
Pressure-test the thesis. Understand the downside. Strengthen the structure.
Every Specialist Can Be Right — and the Decision Can Still Be Wrong.
Attorneys assess legal exposure. Accountants test the numbers. Engineers test what can be built. Bankers structure transactions. Operators know the operating reality. Each perspective matters. The CEO still has to integrate the whole decision. GCP provides the independent strategic counterweight across capital, control, timing, downside, optionality, execution and second-order effects.
Confirmation when the thesis survives. Constructive opposition when it does not.
The objective is not agreement. The objective is the strongest decision.

An illustrative Miami-inspired waterfront district at dawnIllustrative scenario. Not a GCP client project, performance record or recommendation.
WHERE TO BUILD
Two Sites. One Skyline. One Consequential Decision.
A waterfront premium site versus a larger lower-basis inland assemblage. Neither is an automatic winner.
THE CHOICE
A waterfront premium site versus a larger lower-basis inland assemblage. Neither is an automatic winner.
Land basis, buildable area, approvals, construction cost, carrying cost, sales absorption, financing and retained control.
THE GCP QUESTION
Which site still works when the market stops helping you?
Compare the full project, not just the address.
Inspect the Analysis
Where to Build
Which site still works when the market stops helping you?
Compare the full project, not just the address.
- Decision fork
- A waterfront premium site versus a larger lower-basis inland assemblage. Neither is an automatic winner.
- Stakes
- Land basis, buildable area, approvals, construction cost, carrying cost, sales absorption, financing and retained control.
- Decision deliverable
- Site-comparison decision brief; downside cash runway; staged land-control alternatives; conditions to proceed.
Read the complete decision brief
Two Sites. One Skyline. One Consequential Decision.
A waterfront premium site versus a larger lower-basis inland assemblage. Neither is an automatic winner.
The GCP question
Which site still works when the market stops helping you?
What is at stake
Land basis, buildable area, approvals, construction cost, carrying cost, sales absorption, financing and retained control.
What GCP contributes
Compare the full project, not just the address.
The deliverable
Site-comparison decision brief; downside cash runway; staged land-control alternatives; conditions to proceed.
Illustrative scenario. Not a GCP client project, performance record or recommendation.
BEFORE COMMITMENT
Set the conditions before committing the capital.
Site-comparison decision brief; downside cash runway; staged land-control alternatives; conditions to proceed.
Later · Illustrative outcome
Compare the full project, not just the address.
Site-comparison decision brief; downside cash runway; staged land-control alternatives; conditions to proceed.

An illustrative open-pit mine and processing systemIllustrative scenario. Not a GCP client project, performance record or recommendation.
WHAT TO DEVELOP
The Richer Deposit Can Still Be the Worse Investment.
Higher-grade remote deposit versus a lower-grade deposit with stronger infrastructure access.
THE CHOICE
Higher-grade remote deposit versus a lower-grade deposit with stronger infrastructure access.
Recovery assumptions, capex, power, water, transport, operating cost, permissions, timing and commodity exposure.
THE GCP QUESTION
Are you underwriting the resource—or everything required to monetize it?
Underwrite the route from resource to cash flow.
Inspect the Analysis
What to Develop
Are you underwriting the resource—or everything required to monetize it?
Underwrite the route from resource to cash flow.
- Decision fork
- Higher-grade remote deposit versus a lower-grade deposit with stronger infrastructure access.
- Stakes
- Recovery assumptions, capex, power, water, transport, operating cost, permissions, timing and commodity exposure.
- Decision deliverable
- Development alternatives; infrastructure dependency map; staged capex gates; downside and abandonment criteria.
Read the complete decision brief
The Richer Deposit Can Still Be the Worse Investment.
Higher-grade remote deposit versus a lower-grade deposit with stronger infrastructure access.
The GCP question
Are you underwriting the resource—or everything required to monetize it?
What is at stake
Recovery assumptions, capex, power, water, transport, operating cost, permissions, timing and commodity exposure.
What GCP contributes
Underwrite the route from resource to cash flow.
The deliverable
Development alternatives; infrastructure dependency map; staged capex gates; downside and abandonment criteria.
Illustrative scenario. Not a GCP client project, performance record or recommendation.
BEFORE COMMITMENT
Set the conditions before committing the capital.
Development alternatives; infrastructure dependency map; staged capex gates; downside and abandonment criteria.
Later · Illustrative outcome
Underwrite the route from resource to cash flow.
Development alternatives; infrastructure dependency map; staged capex gates; downside and abandonment criteria.

An illustrative New York-inspired harbor at nightIllustrative scenario. Not a GCP client project, performance record or recommendation.
MARINE FUEL
At Fleet Scale, Cents Become Consequence.
Remain exposed to changing fuel prices versus evaluate contract and hedge structures matched to real consumption.
THE CHOICE
Remain exposed to changing fuel prices versus evaluate contract and hedge structures matched to real consumption.
Fuel specification, physical volume or energy units, basis, contract timing, operating margins and collateral liquidity.
THE GCP QUESTION
What fuel-price range keeps the operating plan intact—and what exposure should remain open?
Translate the price change into the correct exposed quantity before considering a hedge.
Inspect the Analysis
Time the fuel purchase. Protect the operating plan.
Fuel procurement is strategic over both short and long horizons. Prices can move during the day; check when the supplier refreshes its quote, how long that quote is valid and the delivery window it covers.
When the delivery schedule allows, a company can leave the purchase open and wait strategically for a lower quote before fuel pickup. If prices fall, procurement cost can fall too. If prices rise, the open exposure costs more.
A firm price for a specified delivery window can provide budget certainty, subject to the supplier’s terms. Compare that certainty with the value and risk of leaving the purchase open.
For a longer horizon, evaluate hedges against expected consumption, fuel specification, location and timing. Basis risk, costs, collateral liquidity and uncertain volume matter. A hedge manages exposure; savings are not assured. Physical procurement and any separately scoped CTA mandate remain distinct decisions.
Illustrative gross fuel-cost sensitivity
Gross cost change = exposed quantity × price change per identical unit.
- Each 0.01 USD per MMBtu moves gross cost by
- Price move the tolerance absorbs, either direction
- EBITDA impact
- Not calculated: gross fuel-cost sensitivity is not EBITDA. An operating and accounting bridge is required.
- Hedge savings
- Not calculated: gross fuel-cost sensitivity is not hedge savings, trading performance or avoided cost.
| Price move per unit | If prices rise | If prices fall |
|---|---|---|
| USD 0.01 / MMBtu | 20,000.00 | -20,000.00 |
| USD 0.05 / MMBtu | 100,000.00 | -100,000.00 |
| USD 0.10 / MMBtu | 200,000.00 | -200,000.00 |
| USD 0.25 / MMBtu | 500,000.00 | -500,000.00 |
| USD 0.50 / MMBtu | 1,000,000.00 | -1,000,000.00 |
| USD 1.00 / MMBtu | 2,000,000.00 | -2,000,000.00 |
- Gross fuel-cost sensitivity is not hedge profit, trading performance, avoided cost or EBITDA.
- A negative price change lowers gross cost; it is not profit.
- LNG, marine distillate, jet fuel and crude are not interchangeable units or exposures.
- Physical fuel specification, geography, timing, basis, volume uncertainty, instrument basis, premium, credit/collateral and pass-throughs are outside this arithmetic.
- The example inputs are hypothetical. They are not the fuel usage of any ship, airline or operator.
BEFORE COMMITMENT
Set the conditions before committing the capital.
Lock a delivery price, wait strategically for a lower quote, or evaluate a longer term hedge. Match each choice to consumption, delivery timing and the operating plan.
THE ECONOMIC CONSEQUENCE
Translate the price change into the correct exposed quantity before considering a hedge.
Gross fuel-cost sensitivity; basis and volume review; operating-plan consequences; separately scoped hedge and liquidity analysis.

An illustrative offshore development and support systemIllustrative scenario. Not a GCP client project, performance record or recommendation.
WHERE TO COMMIT
The Reservoir Is Only the Beginning.
Develop an infrastructure-adjacent field versus commit to a larger remote development.
THE CHOICE
Develop an infrastructure-adjacent field versus commit to a larger remote development.
Resource uncertainty, facilities, offload logistics, development cost, schedule, price sensitivity and financing.
THE GCP QUESTION
Which assumption has to hold for the project to earn its cost of capital?
Connect the development plan to the downside case.
Inspect the Analysis
Where to Commit
Which assumption has to hold for the project to earn its cost of capital?
Connect the development plan to the downside case.
- Decision fork
- Develop an infrastructure-adjacent field versus commit to a larger remote development.
- Stakes
- Resource uncertainty, facilities, offload logistics, development cost, schedule, price sensitivity and financing.
- Decision deliverable
- Project-gate decision memo; infrastructure dependencies; price/cost sensitivities; phased commitment conditions.
Read the complete decision brief
The Reservoir Is Only the Beginning.
Develop an infrastructure-adjacent field versus commit to a larger remote development.
The GCP question
Which assumption has to hold for the project to earn its cost of capital?
What is at stake
Resource uncertainty, facilities, offload logistics, development cost, schedule, price sensitivity and financing.
What GCP contributes
Connect the development plan to the downside case.
The deliverable
Project-gate decision memo; infrastructure dependencies; price/cost sensitivities; phased commitment conditions.
Illustrative scenario. Not a GCP client project, performance record or recommendation.
BEFORE COMMITMENT
Set the conditions before committing the capital.
Project-gate decision memo; infrastructure dependencies; price/cost sensitivities; phased commitment conditions.
Later · Illustrative outcome
Connect the development plan to the downside case.
Project-gate decision memo; infrastructure dependencies; price/cost sensitivities; phased commitment conditions.

An illustrative hyperscale campus and its power infrastructure at nightIllustrative scenario. Not a GCP client project, performance record or recommendation.
WHAT CONSTRAINS GROWTH
The Scarce Asset May Not Be the Data Center.
Lower-cost land with uncertain power timing versus a higher-cost site with credible deliverable capacity.
THE CHOICE
Lower-cost land with uncertain power timing versus a higher-cost site with credible deliverable capacity.
Interconnection timing, deliverability, power contracts, cooling, construction, utilization, customer commitments and stranded capacity.
THE GCP QUESTION
What controls the return: land, deliverable power, interconnection, cooling, compute—or time?
Identify the dependency that controls revenue timing.
Inspect the Analysis
What Constrains Growth
What controls the return: land, deliverable power, interconnection, cooling, compute—or time?
Identify the dependency that controls revenue timing.
- Decision fork
- Lower-cost land with uncertain power timing versus a higher-cost site with credible deliverable capacity.
- Stakes
- Interconnection timing, deliverability, power contracts, cooling, construction, utilization, customer commitments and stranded capacity.
- Decision deliverable
- Power-to-revenue dependency map; time-to-service cases; customer/energy contract alignment; stage-gate capital plan.
Read the complete decision brief
The Scarce Asset May Not Be the Data Center.
Lower-cost land with uncertain power timing versus a higher-cost site with credible deliverable capacity.
The GCP question
What controls the return: land, deliverable power, interconnection, cooling, compute—or time?
What is at stake
Interconnection timing, deliverability, power contracts, cooling, construction, utilization, customer commitments and stranded capacity.
What GCP contributes
Identify the dependency that controls revenue timing.
The deliverable
Power-to-revenue dependency map; time-to-service cases; customer/energy contract alignment; stage-gate capital plan.
Illustrative scenario. Not a GCP client project, performance record or recommendation.
BEFORE COMMITMENT
Set the conditions before committing the capital.
Power-to-revenue dependency map; time-to-service cases; customer/energy contract alignment; stage-gate capital plan.
Later · Illustrative outcome
Identify the dependency that controls revenue timing.
Power-to-revenue dependency map; time-to-service cases; customer/energy contract alignment; stage-gate capital plan.

An illustrative aerospace integration and deployment systemIllustrative scenario. Not a GCP client project, performance record or recommendation.
WHICH FUTURE TO FUND
Technical Success Does Not Automatically Earn the Next Billion.
Scale deployment immediately versus fund a measured phase after commercial and technical milestones.
THE CHOICE
Scale deployment immediately versus fund a measured phase after commercial and technical milestones.
Demand, contracts, manufacturing scale, deployment schedule, cash runway and evidence required for the next financing.
THE GCP QUESTION
What evidence earns the next phase of capital?
Separate technical achievement from the next capital commitment.
Inspect the Analysis
Which Future to Fund
What evidence earns the next phase of capital?
Separate technical achievement from the next capital commitment.
- Decision fork
- Scale deployment immediately versus fund a measured phase after commercial and technical milestones.
- Stakes
- Demand, contracts, manufacturing scale, deployment schedule, cash runway and evidence required for the next financing.
- Decision deliverable
- Milestone-funded growth plan; customer evidence requirements; capital runway; commercial scale/no-scale conditions.
Read the complete decision brief
Technical Success Does Not Automatically Earn the Next Billion.
Scale deployment immediately versus fund a measured phase after commercial and technical milestones.
The GCP question
What evidence earns the next phase of capital?
What is at stake
Demand, contracts, manufacturing scale, deployment schedule, cash runway and evidence required for the next financing.
What GCP contributes
Separate technical achievement from the next capital commitment.
The deliverable
Milestone-funded growth plan; customer evidence requirements; capital runway; commercial scale/no-scale conditions.
Illustrative scenario. Not a GCP client project, performance record or recommendation.
BEFORE COMMITMENT
Set the conditions before committing the capital.
Milestone-funded growth plan; customer evidence requirements; capital runway; commercial scale/no-scale conditions.
Later · Illustrative outcome
Later · Launch and ascent
Later · Orbital deployment
Separate technical achievement from the next capital commitment.
Milestone-funded growth plan; customer evidence requirements; capital runway; commercial scale/no-scale conditions.
A Few Basis Points. A Few Cents. A Seven-Figure Decision.
At enterprise scale, modest changes in yield, fuel, currency, freight, working capital or contract terms can move millions of dollars through the business.
Capital Should Be Available When the Business Needs It.
Leave eligible reserves undifferentiated versus match their availability to obligations and a separately approved treasury mandate.
The GCP question
Which cash is truly unrestricted—and when could the company need it?
What is at stake
Operating cash, restrictions, payroll, taxes, committed capex, strategic optionality and mark-to-market liquidity.
What GCP contributes
Classify ownership and timing before discussing investment return.
The deliverable
Corporate liquidity map; obligation calendar; investment-policy questions; separately scoped advisory review.
Illustrative scenario. Not a GCP client project, performance record or recommendation.
Inspect the Analysis
Corporate Liquidity Mapper
Net liquidity = unrestricted corporate cash − identified disjoint needs.
- Potential surplus, a scenario residual
- Funding gap
- Total identified needs
- Investment recommendation
- Not provided: a residual is not an allocation. Eligible reserves need a separately approved treasury mandate.
A positive residual is a candidate amount for a separately scoped review, not an instruction to invest it.
| Bucket | Amount | Share of unrestricted cash |
|---|---|---|
| Operating and payroll needs | 35,000,000.00 | 35.00% |
| Debt service and maturities | 20,000,000.00 | 20.00% |
| Committed capital expenditure | 15,000,000.00 | 15.00% |
| Taxes and regulatory reserves | 8,000,000.00 | 8.00% |
| Other identified obligations | 2,000,000.00 | 2.00% |
- Only properly classified, eligible firm-owned capital belongs in this example.
- Customer funds, exchange participant collateral, custodial assets, margin, restricted or encumbered cash and required reserves are outside this example.
- The output is a scenario residual, not a recommendation to buy securities.
- Duplicate or overlapping obligations overstate the need; the confirmation prompts the review, it does not prove the accounting.
- The example inputs are hypothetical. They are not any company's balances.
The Lowest Quote Can Still Be the Most Expensive Contract.
Lower initial unit quote versus a slightly higher quote with different currency, logistics, quality and contractual optionality.
The GCP question
What does each supplier cost over the full commitment—not just on signing day?
What is at stake
Contractual currency, FX path, freight, customs-value base, quality, lead times, working capital and termination terms.
What GCP contributes
Compare the same service and units under both favorable and adverse assumptions.
The deliverable
Visible total-cost bridge; FX breakpoints; scenario reversal; contract and sourcing options.
Illustrative scenario. Not a GCP client project, performance record or recommendation.
Inspect the Analysis
Sourcing Total-Cost / FX Comparator
Purchase per unit = quote × functional-currency units per one quote-currency unit.
- Supplier A present value
- Supplier B present value
- A − B over the contract
- A − B in present value, quote currencies up
- A − B in present value, quote currencies down
- Supplier A annual cost
- Supplier B annual cost
- Supplier recommendation
- Not provided: the arithmetic compares scenarios; concentration, reliability, termination rights and contract terms decide alongside it.
Supplier A has the lower purchase price per unit and the higher total cost.
| Component | Supplier A | Supplier B |
|---|---|---|
| Purchase (quote × FX) | 10.0000 | 10.5000 |
| Duty (customs value × rate) | 1.0000 | 0.0000 |
| Freight | 2.0000 | 1.0000 |
| Quality allowance | 1.0000 | 0.5000 |
| Working-capital allowance | 0.5000 | 0.2500 |
| Cost per unit | 14.5000 | 12.2500 |
| Case | Supplier A | Supplier B | A − B |
|---|---|---|---|
| Quote currencies up | 3,994.50 | 3,156.94 | 837.56 |
| Baseline | 3,736.79 | 3,156.94 | 579.85 |
| Quote currencies down | 3,479.08 | 3,156.94 | 322.14 |
| Year | Supplier A | Supplier B | A present value | B present value |
|---|---|---|---|---|
| 1 | 1,450.00 | 1,225.00 | 1,342.59 | 1,134.26 |
| 2 | 1,450.00 | 1,225.00 | 1,243.14 | 1,050.24 |
| 3 | 1,450.00 | 1,225.00 | 1,151.06 | 972.44 |
- Duty applies to the declared customs-value base only, never to every operating cost.
- The FX move is a stated scenario, not a forecast; a quote in the functional currency does not move.
- Both suppliers are compared on the same functional currency, quantity, years and discount basis.
- Supplier concentration, quality reliability, termination rights and contract terms are not priced here.
- Illustrative arithmetic, not customs, tax or legal advice, and not a supplier recommendation.
- The example inputs are hypothetical.
A Fleet Order Is a View on the World Years From Now.
Commit to a large newbuild program now versus stage deliveries, charter capacity or retain options.
The GCP question
How much of the next trade cycle should the company commit to today?
What is at stake
Delivery timing, utilization, charter alternatives, financing, residual value, fuel exposure and contracted demand.
What GCP contributes
Price the commitment and the option to wait.
The deliverable
Fleet-capital decision note; utilization breakpoints; charter-versus-own scenarios; staged delivery and exit terms.
Illustrative scenario. Not a GCP client project, performance record or recommendation.
Fuel Exposure Moves Through the Entire Network.
Unmanaged or mismatched fuel exposure versus a consumption-aligned risk framework.
The GCP question
How does the fuel scenario change route economics, liquidity and the operating plan?
What is at stake
Fuel specification, physical basis, uncertain volume, timing, hedge collateral and operating response.
What GCP contributes
Connect fuel sensitivity to the business plan without calling it guaranteed savings.
The deliverable
Unit-explicit fuel-cost sensitivity; network scenario implications; separately engaged hedge/collateral review.
Illustrative gross fuel-cost sensitivity
Gross cost change = exposed quantity × price change per identical unit.
Illustrative scenario. Not a GCP client project, performance record or recommendation.
Inspect the Analysis
Illustrative gross fuel-cost sensitivity
Gross cost change = exposed quantity × price change per identical unit.
- Each 0.01 USD per US gallon moves gross cost by
- Price move the tolerance absorbs, either direction
- EBITDA impact
- Not calculated: gross fuel-cost sensitivity is not EBITDA. An operating and accounting bridge is required.
- Hedge savings
- Not calculated: gross fuel-cost sensitivity is not hedge savings, trading performance or avoided cost.
| Price move per unit | If prices rise | If prices fall |
|---|---|---|
| USD 0.01 / US gallon | 400,000.00 | -400,000.00 |
| USD 0.05 / US gallon | 2,000,000.00 | -2,000,000.00 |
| USD 0.10 / US gallon | 4,000,000.00 | -4,000,000.00 |
| USD 0.25 / US gallon | 10,000,000.00 | -10,000,000.00 |
| USD 0.50 / US gallon | 20,000,000.00 | -20,000,000.00 |
| USD 1.00 / US gallon | 40,000,000.00 | -40,000,000.00 |
- Gross fuel-cost sensitivity is not hedge profit, trading performance, avoided cost or EBITDA.
- A negative price change lowers gross cost; it is not profit.
- LNG, marine distillate, jet fuel and crude are not interchangeable units or exposures.
- Physical fuel specification, geography, timing, basis, volume uncertainty, instrument basis, premium, credit/collateral and pass-throughs are outside this arithmetic.
- The example inputs are hypothetical. They are not the fuel usage of any ship, airline or operator.
Fleet Capital Architecture
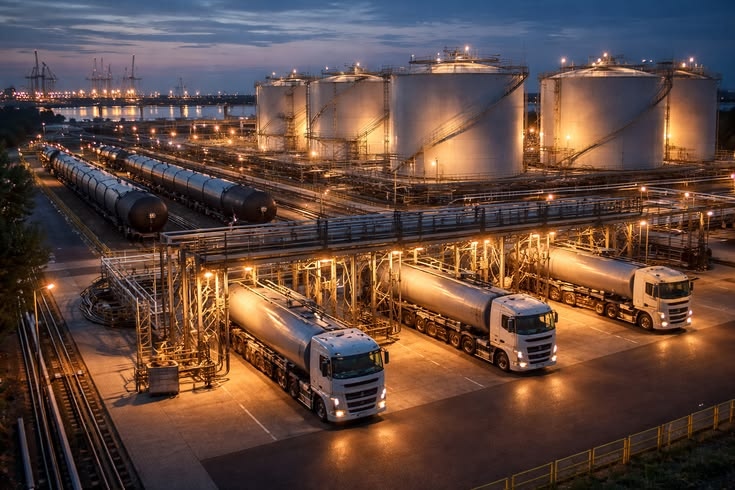
Industrial terminal · storage, loading and fleet capacity.
- Tanker / carriage
- Own
- Tractor / horse
- Lease
Illustrative operating context. Fleet counts below are calculated from the applied assumptions.
Precision Economics · Operating Capital Architecture
Own the Carriage.
Rent the Horse.
Buy depreciated longevity.
Lease mechanical intensity.
Build more productive fleet capacity with the same permanent capital.
Preserve the liquidity required to operate them.
Complete new rigs can consume a founder's capital before the fleet reaches meaningful scale. Concentrate ownership where a sound used specialized tanker offers an economic edge. Keep the mileage-intensive tractor fresh through leasing when the actual terms support it.
Same money · Active operating fleet
How much active fleet can the same dollar actually build?
- Same starting permanent capital
Applied assumptions · the same budget funds both structures.
Conventional new ownership
Buy both components new.
supported active rig- Permanent capital per active unit
Required equipment cash for one operable rig in this case.
- Equipment capital committed
- Operating liquidity retained
Starting capital less equipment capital.
- Working cash required
Operating funding, before the protected liquidity reserve.
- Monthly fixed cash
- Required break-even utilization
Expected realized: 78.0800%.
- Annual operating cash contribution
- Uncommitted liquidity
After operating, protected and first-year equipment funding. Funding gap: USD 0.00.
Carriage / Horse hybrid
Own the tanker. Lease fresh power.
supported active rigs- Permanent capital per active unit
Required equipment cash for one operable rig in this case.
- Equipment capital committed
- Operating liquidity retained
Starting capital less equipment capital.
- Working cash required
Operating funding, before the protected liquidity reserve.
- Monthly fixed cash
- Required break-even utilization
Expected realized: 77.4400%.
- Annual operating cash contribution
- Uncommitted liquidity
After operating, protected and first-year equipment funding. Funding gap: USD 0.00.
- Fleet capacity multiplier
Conventional permanent capital per active rig ÷ hybrid permanent capital per active rig in this case.
- Active unit multiplier
Hybrid supported active rigs ÷ conventional supported active rigs in this case.
Rig symbols follow the calculated active counts. Each case tests funding, customer demand, drivers, dispatch, terminal capacity, insurance and positive incremental operating cash. The hybrid can support fewer rigs or lose its economic edge.
01 · The carriage · own
Buy capacity where the acquisition asymmetry survives inspection.
A sound used tanker can retain useful specialized service after its first owner absorbs depreciation. Price the complete preparation: tank integrity, corrosion, compartments, loading compatibility, valves, pumps, meters, running gear, brakes, tires and certification.
- Replacement-cost discount
- Fully prepared used-tanker cost
Acquisition + inspection/reconditioning + fees; financing is evaluated separately.
- Discount after preparation
- Supported service-life assumption
Requires condition and certification review.
Required work can erase the discount. A tanker is never maintenance-free.
02 · The horse · lease
Keep the mechanical workload fresh, predictable and replaceable.
Mileage and engine hours accumulate in the drivetrain, transmission, emissions systems, electronics, cooling, suspension and steering. A cheap aging tractor can become expensive when road failure disrupts loads, drivers and customer service.
- Entered base tractor lease
Per tractor / month; adverse-case rates are tested in the active comparison.
- Entered lease term
Maintenance, warranty, replacement vehicles, mileage charges and exit costs depend on the actual agreement. This model supplies no blanket warranty or uptime promise.
Compare the active operating architectures
Four structures. The economics decide.
Supported active counts change with the selected case. Detailed target economics below test your requested 4 rigs. A larger fleet must preserve liquidity and earn positive incremental cash.
C · Own used tanker + lease fresh tractor
Base case · Your target fleet
Activated operating capacity
4active units4 leased tractors · 4 committed power units
Working cash required
USD 159,233.49USD 338,000.00 retained after equipment. Protected liquidity and every operating funding bucket must still fit.
Operating liquidity is part of active capacity
Preserve the cash that keeps the fleet working.
- Capital available
- Equipment capital committed
- Operating liquidity retained
- Working cash required
- Protected liquidity required
- Uncommitted liquidity
After first-year equipment funding. Funding gap: USD 0.00.
See the operating cash commitments
Float and receivable funding must be additional, disjoint amounts. Reserves are cash held for operation and disruption, rather than expense charged twice.
- Fuel float
- Payroll float
- DEF, tolls & other operating float
- Receivable funding
- Insurance deposits
- Terminal deposits
- Inventory / product exposure
- Active-equipment maintenance reserve
- Optional dormant-tanker maintenance reserve
- Downtime cash reserve
- Minimum protected liquidity
- Emergency liquidity
- Total protected liquidity
- Total operating working cash
- Total startup funding required
First-year replacement & renewal funding
Supported fleet counts protect the peak additional equipment cash required in the first year. Future revenue collection timing is not assumed. This protected cash is separate from operating expense and the initial equipment capital quote.
- Additional equipment liquidity to protect
Peak chronological cash call after supplied sale and deposit-return credits.
- Replacement acquisition cash
- Replacement loan payoff cash
- Replacement disposal cash
- Supported replacement sale credits
- Lease renewal cash outflows
- Lease renewal deposit returns
No scheduled replacement or renewal cash call falls within this first year under the applied terms.
- Permanent capital per active unit
- Equipment cash committed
- Monthly fixed cash
First-year monthly average, including actual debt/lease payments.
- Cash break-even utilization
Realized utilization: 77.4400%.
- Gross contribution per active unit
Revenue less variable service costs; fixed cash and downtime are evaluated separately.
- Annual gross contribution
- Annual variable operating cash
- Annual total operating cash cost
- Annual delivered revenue
- Annual operating cash contribution
Capital purchase, replacement and residual are also evaluated below.
- Cost / total mile
- Cost / loaded mile
- Cost / revenue operating day
- Annual total / loaded / empty miles
- Constant-burn liquidity runway
No finite exhaustion is calculated for a cash-generating case, or where a complete burn is unavailable.
Drivers available5
Terminal / loading capacity5
Dispatch capacity5
Insured operating units5
Regulatory / compliance capacity5
Compatible, certified tanker capacity6
Fresh tractors available to lease6
Active scale ladder · Base case
Does the next truck create profit—or merely create fleet size?
Each step adds one requested rig to the previous fleet. Demand, driver capacity and working cash can prevent that rig from adding productive capacity or positive operating cash.
Unit 1
Passes the current tests1 additional active rig · 1 active in the cumulative fleet
- Additional equipment capital
- Additional working cash
- Additional first-year equipment funding
Separate liquidity for replacement and renewal calls, beyond initial equipment and operating cash.
- Additional monthly fixed cash
- Minimum incremental utilization
- Marginal operating cash / year
- Cumulative uncommitted liquidity
Funding gap: USD 0.00.
Unit 1 operating requirements
Incremental values compare this fleet with the immediately preceding fleet, under the same case.
- Additional annual revenue
- Additional annual gross contribution
- Additional annual cash cost
- Additional downtime reserve
- Additional annual downtime cash cost
- Additional drivers required
- Additional annual driver cash
- Additional annual insurance
- Additional customer demand
- Incremental realized utilization
Unit 2
Passes the current tests1 additional active rig · 2 active in the cumulative fleet
- Additional equipment capital
- Additional working cash
- Additional first-year equipment funding
Separate liquidity for replacement and renewal calls, beyond initial equipment and operating cash.
- Additional monthly fixed cash
- Minimum incremental utilization
- Marginal operating cash / year
- Cumulative uncommitted liquidity
Funding gap: USD 0.00.
Unit 2 operating requirements
Incremental values compare this fleet with the immediately preceding fleet, under the same case.
- Additional annual revenue
- Additional annual gross contribution
- Additional annual cash cost
- Additional downtime reserve
- Additional annual downtime cash cost
- Additional drivers required
- Additional annual driver cash
- Additional annual insurance
- Additional customer demand
- Incremental realized utilization
Unit 3
Passes the current tests1 additional active rig · 3 active in the cumulative fleet
- Additional equipment capital
- Additional working cash
- Additional first-year equipment funding
Separate liquidity for replacement and renewal calls, beyond initial equipment and operating cash.
- Additional monthly fixed cash
- Minimum incremental utilization
- Marginal operating cash / year
- Cumulative uncommitted liquidity
Funding gap: USD 0.00.
Unit 3 operating requirements
Incremental values compare this fleet with the immediately preceding fleet, under the same case.
- Additional annual revenue
- Additional annual gross contribution
- Additional annual cash cost
- Additional downtime reserve
- Additional annual downtime cash cost
- Additional drivers required
- Additional annual driver cash
- Additional annual insurance
- Additional customer demand
- Incremental realized utilization
Unit 4
Passes the current tests1 additional active rig · 4 active in the cumulative fleet
- Additional equipment capital
- Additional working cash
- Additional first-year equipment funding
Separate liquidity for replacement and renewal calls, beyond initial equipment and operating cash.
- Additional monthly fixed cash
- Minimum incremental utilization
- Marginal operating cash / year
- Cumulative uncommitted liquidity
Funding gap: USD 0.00.
Unit 4 operating requirements
Incremental values compare this fleet with the immediately preceding fleet, under the same case.
- Additional annual revenue
- Additional annual gross contribution
- Additional annual cash cost
- Additional downtime reserve
- Additional annual downtime cash cost
- Additional drivers required
- Additional annual driver cash
- Additional annual insurance
- Additional customer demand
- Incremental realized utilization
Unit 5
Fails the current tests1 additional active rig · 5 active in the cumulative fleet
- Additional equipment capital
- Additional working cash
- Additional first-year equipment funding
Separate liquidity for replacement and renewal calls, beyond initial equipment and operating cash.
- Additional monthly fixed cash
- Minimum incremental utilization
- Marginal operating cash / year
- Cumulative uncommitted liquidity
Funding gap: USD 0.00.
Unit 5 adds fleet size without positive incremental operating cash contribution.
Unit 5 operating requirements
Incremental values compare this fleet with the immediately preceding fleet, under the same case.
- Additional annual revenue
- Additional annual gross contribution
- Additional annual cash cost
- Additional downtime reserve
- Additional annual downtime cash cost
- Additional drivers required
- Additional annual driver cash
- Additional annual insurance
- Additional customer demand
- Incremental realized utilization
- Unit 5 adds fleet size without positive incremental operating cash contribution.
- Incremental loaded demand is below this unit's cash break-even requirement.
Your requested incremental unit · Base case
Does unit 5 earn its place?
- Additional equipment capital
- Additional working capital
- Additional annual revenue
- Additional annual cash cost
- Incremental operating cash
- Minimum incremental utilization
Extra loaded miles required: 33,645.39.
The additional unit does not pass this case's capital, demand and cash tests.
- Unit 5 adds fleet size without positive incremental operating cash contribution.
- Incremental loaded demand is below this unit's cash break-even requirement.
Availability has an economic price
True downtime cost
An apparently cheap tractor can become the expensive choice once lost loads, idle drivers, repairs and disrupted customers are counted.
- Known downtime cash expense
- Lost gross contribution
Mileage displacement is counted once.
- Full annual downtime cost
- Tractor · Tow
- USD 1,200.00
- Tractor · Repair
- USD 6,000.00
- Tractor · Replacement equipment
- USD 0.00
- Tractor · Additional driver idle cash
- USD 0.00
- Tractor · Service / contract cost
- USD 0.00
- Tractor · Management / operational disruption
- USD 0.00
- Tanker · Tow
- USD 0.00
- Tanker · Repair
- USD 4,800.00
- Tanker · Replacement equipment
- USD 0.00
- Tanker · Additional driver idle cash
- USD 0.00
- Tanker · Service / contract cost
- USD 0.00
- Tanker · Management / operational disruption
- USD 0.00
- Lost gross contribution · counted once
- USD 28,876.80
Acquisition through exit
Three horizons. The full cash commitment.
Each horizon settles outstanding financing and lease obligations. Residuals and returned deposits are credited separately. A negative net cash requirement means scenario cash generation.
3years
- Gross cash outflows
- Delivered revenue
- Replacement sale proceeds
- Terminal asset residual
- Returned lease deposits
- Loan payoff in cash outflows
- Requirement before revenue
- Net cash requirement
- After-tax net cash requirement
Requires supported tax assumptions for this exact fleet and case.
5years
- Gross cash outflows
- Delivered revenue
- Replacement sale proceeds
- Terminal asset residual
- Returned lease deposits
- Loan payoff in cash outflows
- Requirement before revenue
- Net cash requirement
- After-tax net cash requirement
Requires supported tax assumptions for this exact fleet and case.
7years
- Gross cash outflows
- Delivered revenue
- Replacement sale proceeds
- Terminal asset residual
- Returned lease deposits
- Loan payoff in cash outflows
- Requirement before revenue
- Net cash requirement
- After-tax net cash requirement
Requires supported tax assumptions for this exact fleet and case.
Economics first. Tax attributes second. Never buy a bad asset for a tax deduction.
Reviewed tax cash schedule
After-tax totals require an explicitly supported professional schedule for this exact fleet scope.
No Section 179, bonus-depreciation percentage, asset life, entity treatment or deduction rule is supplied by this tool. A changed fleet count does not inherit an old tax result. Review an actual transaction with a qualified tax professional.
Apply the complete reviewed schedule together with the current assumptions.
Optional reserve capacity
Solve the active fleet first. Then test whether an unusually attractive tanker acquisition, reasonable carrying cost and credible customer growth justify extra carriages before more power units are activated.
Own dormant capacity only when its carrying costs and eventual activation economics earn their place.
Choose E to inspect its complete target economics, cash commitments, scale ladder and exit horizons above.
Active operating fleet
4active units4 leased tractors · 4 committed power units
Optional controlled carriage capacity
6owned tankers2 dormant tankers · 0 leased tankers
Storage, insurance, inspection, certification, maintenance, deterioration and tied-up capital remain economic costs. Leasing availability and a future customer are assumptions to test.
Structure E can own more carriages than it activates.
Reserve settings are an optional extension of the same funding pool.
What the numbers mean
The strongest architecture is the one whose complete economics, operating conditions and liquidity survive review.
- Equipment capital
- Cash committed to equipment at activation: cash purchase or financed down payment, inspection/reconditioning, acquisition/origination fees and lease security deposits. Borrowed principal is disclosed through debt service and terminal payoff; working capital is separate.
- Capacity multiplier
- For the selected case: conventional permanent capital REQUIRED for one physically operable ACTIVE rig ÷ hybrid requirement. A capital-efficient rig can still be unprofitable or unaffordable. Active unit multiplier separately divides economically supported hybrid units by conventional units under the same cash pool and case. Baseline aliases preserve the original interface. Zero or unavailable denominators stay unavailable; no fixed 2-to-5 promise exists.
- Supported units
- Maximum units under the cash pool, first-year equipment prefunding and explicit physical limits. Economically supported units additionally require a positive whole-fleet cash contribution and positive incremental contribution. A funded fleet can still be overbuilt.
- Retained working capital
- Available cash less activation equipment commitments and protected minimum/emergency liquidity; compare this retained funding with the separately calculated operating working-capital requirement. Uncommitted liquidity also deducts operating working cash and the known first-year equipment prefunding reserve. An incomplete first-year ledger remains explicitly unavailable.
- First-year equipment funding
- Pre-fund the peak cumulative first-year equipment capital calls: replacement cash/down payments and fees, outstanding loan settlements and payoff fees, disposal, and actual lease renewal outflows, less only supplied sale/refund credits at those events. Events occur before the stated month, after the previous equipment cycle completes. Activation cash and terminal exit are excluded. No future operating-profit collection is assumed. This reserve is a funding commitment, not another annual expense or horizon charge; unknown required sale or service terms block fleet support.
- Operating cash
- Delivered revenue less variable operating cost, fixed cash costs including actual first-year debt/lease payments, additional downtime cash and separately supplied missed-load contribution. Monthly fixed cash is the first-year monthly average. Asset capital consumption, replacements and final payoff appear in horizon costs.
- Cost of service
- Annual operating cash cost divided by actual delivered total or loaded miles. Cost per operating day uses service days implied by actual delivered miles at the stated full-utilization daily mileage. Cash purchase price is capital, so review horizon costs too. Unknown downtime expense makes full cost ratios unavailable.
- Break-even utilization
- First delivered loaded-mile utilization that covers annual fixed cash, downtime cash, variable costs and actual excess-mile terms. Excess-mile charges can cause losses at higher mileage, so judge the actual contribution as well. This threshold precedes downtime and demand limits; an unattainable or undefined threshold is unavailable.
- The additional unit
- Each scale-ladder step is Fleet N minus Fleet N−1 in the same case, demand pool and cash pool. It exposes activation capital, separate first-year equipment prefunding, fixed obligations, working capital, entered downtime reserve/cost, drivers, insurance and delivered demand. Extra equipment can add cost while producing no extra revenue. Minimum incremental utilization is the extra loaded service needed to cover its incremental operating cash cost; it does not fund an unmet equipment capital call.
- True downtime
- Tow + repair + replacement equipment + additional driver idle + lost gross contribution + service/contract cost + operational/management disruption. Lost gross is the no-downtime gross ledger less actual gross, including avoided variable costs and both tanker/tractor lease overage charges, clamped at zero. Supplier-paid replacement cost is credited only when supplied. This explanatory opportunity loss is not charged again in annual cash.
- Horizon cash requirement
- Gross cash outflows less replacement sales, terminal asset residual and returned lease deposits gives cash requirements before revenue. Subtract delivered revenue for net cash requirement; a negative result is scenario net cash generation. Each horizon exits, pays outstanding loans and settles lease obligations.
- Residual assumptions
- Terminal residual uses equipment age since the latest replacement, not the fleet's calendar age. Disposal fees and financing payoff are separate. Missing residuals remain unknown; useful service and replacement coverage must last through the horizon.
- Liquidity runway
- Uncommitted liquidity divided by monthly operating cash burn. A cash-generating case has no finite modeled exhaustion and returns unavailable; this is a constant-rate view, not a weekly cash-flow forecast.
- Tax support
- User-supplied annual cash-tax effects, timing, basis, business use, limitations and professional support govern tax outputs. Positive effects are cash tax payments, negative effects cash tax benefits. No tax estimate is carried into downside/stress without its own reviewed schedule.
Scenario assumptions & boundaries
Calculated outcomes are conditional. No financing approval, customer demand, certification, insurance or tax eligibility is established here.
- Every example price, cost, service life, residual and operating input is hypothetical. Replace assumptions with actual quotes, inspection evidence, contracts and operating records.
- A–D compare active fleet structures first. E is an optional reserve-capacity extension after active economics are established. One power unit needs one driver and one compatible certified tanker; dispatch and physical constraints limit delivered service.
- Loaded and empty miles move proportionately with delivered service. Annual contract revenue is prorated with delivered loaded miles; this is the stated scenario, not a claim about a particular customer agreement.
- Annual demand, revenue rates, operating costs and working-capital days stay constant within each case. The 3/5/7-year model has no automatic inflation, growth, seasonality or discount rate.
- Replacement acquisitions repeat the explicitly supplied terms. A lease renews only when same-term renewal is explicitly assumed; unknown renewal, residual or useful-life coverage makes dependent horizon totals unavailable.
- Fuel, payroll and other operating float are additional to receivable funding. Maintenance, downtime, emergency and minimum-liquidity buckets must be disjoint. Working capital and protected liquidity are funding commitments, not expenses charged again in horizon cash costs.
- First-year equipment capital calls are conservatively pre-funded separately from activation capital and operating working cash. The reserve is the peak cumulative replacement/renewal cash call after only supplied sale/refund credits. Future operating profit is not assumed collected in time; missing required first-year sale or service terms block supported activation.
- Contracted loads plus separately expected uncontracted loads cap demand only when their loaded mileage is supplied. Unknown load-plan values do not manufacture customers. Losing the largest customer requires a supplied concentration percentage; otherwise dependent adverse outputs are unavailable.
- Lease and insurance factors, extra receivable/fuel days, driver/terminal shortages, customer loss and one-time owned-tanker reconditioning surprises are explicitly entered scenario assumptions. They do not assert a change to an actual contract or supplier quote.
- Downtime cash amounts are additional to scheduled maintenance, payroll and lease costs. Lost gross contribution reflects displaced loaded miles once; additional missed-load contribution must cover separate losses.
- Equipment cash outflows include down payments, fees, scheduled debt service, replacements, loan payoff, lease deposits, excess mileage and contractual exit. Sale residuals and deposit refunds are credited separately; proceeds are assumptions.
- After-tax totals require an explicitly supported professional schedule for the exact fleet scope. No depreciation rule, deduction percentage or tax eligibility is inferred. Review an actual transaction with a qualified tax professional.
Read the complete decision brief
Fleet Capital Architecture
Own the Carriage. Rent the Horse.
Buy depreciated longevity. Lease mechanical intensity. Build more productive fleet capacity with the same permanent capital. Preserve the liquidity required to operate them.
Same capital. More active revenue-producing capacity.
How Much Active Fleet Can the Same Dollar Actually Build?
A new operator can commit scarce capital to complete new tractor-and-tanker combinations before the business reaches meaningful fleet scale. Fleet Capital Architecture asks which part of the rig deserves permanent capital and which part should remain flexible. Sound used specialized tankers plus fresh leased power may support more active revenue-producing units from the same capital pool when actual prices, lease terms and operating conditions justify it. The goal is productive units on the road without starving the business of liquidity, reliability or operating capacity.
Compare four primary active-fleet architectures under the same starting permanent capital and equivalent service requirements. A: conventional new ownership, purchasing a new tanker and a new tractor. B: used full ownership, purchasing a used tanker and used tractor with their condition, repair, replacement and residual exposure. C: the Carriage / Horse hybrid, owning an attractively priced specialized tanker and leasing comparatively fresh power under actual terms. D: fully variable, leasing or renting both where commercially available and comparable. Calculate supported active units; do not predetermine the winner. A high lease payment, restrictive mileage allowance, expensive reconditioning, weak demand or inadequate liquidity can make the hybrid lose.
Counts come from the visitor’s assumptions. A comparison may produce two versus five, two versus three, equal counts or fewer viable hybrid units. Those are calculated conditional outputs, never a promise to turn two trucks into five. This is a Precision Economics case study within Executive Strategic Counsel and Business Consulting.
The carriage: buy specialized capacity where ownership earns its place
A sound used tanker can sometimes offer an exceptional discount to an equivalent new build while retaining useful service life. How much productive specialized capacity is each dollar buying? Examine tank integrity, corrosion, compartments, product and loading compatibility, valves, pumps, meters, running gear, suspension, brakes, tires, inspection, certification, compliance, storage and insurance. Include inspection and reconditioning in the fully prepared cost, together with supported remaining useful service life and expected residual or disposal value. Tankers are not maintenance-free; required work can erase the apparent discount.
Replacement-cost discount = (equivalent new tanker cost − used tanker acquisition cost) ÷ equivalent new tanker cost. A valid discount requires a comparable positive replacement-cost basis. Evaluate that discount alongside fully prepared cost and supported useful life. Used equipment is not automatically a bargain.
The horse: keep mechanical intensity fresh and predictable
The tractor absorbs daily mileage and engine hours, engine and drivetrain workload, transmission wear, emissions and aftertreatment exposure, electronics, cooling, suspension, steering, tires and roadside-failure costs. An inexpensive aging tractor can become expensive in total economic cost when lost availability and customer disruption are included. Leasing a comparatively fresh power unit may bound replacement or residual exposure where the actual contract supports it.
Enter deposits, monthly payments, term, mileage allowance, excess-mile charges, early termination, scheduled replacement and actual maintenance, warranty and replacement-vehicle provisions. Maintenance and warranty are not included in every lease. Evaluate uptime and replacement economics from supported assumptions rather than promising reliability.
Preserve working capital while scaling
Capital available − equipment capital committed = operating liquidity retained. Then test whether that liquidity can operate the proposed active fleet while preserving the selected minimum reserve. Acquisition count is not supported operating capacity. An equipment-rich business can still be liquidity-poor.
Include fuel float, payroll, insurance and terminal deposits, receivables delays, tolls, DEF where relevant, scheduled maintenance, compliance, inventory or product exposure where applicable, maintenance and emergency reserves, and unexpected repair or replacement needs. Financing rates, terms and down payments affect both initial commitment and ongoing obligations. A larger fleet with insufficient operating liquidity must fail the constraint or scale down. Show working capital remaining as prominently as the equipment acquired.
The economic unit ladder: does the next truck create profit?
How many active revenue units can this balance sheet intelligently support? Test each additional active rig with its incremental capital, monthly fixed obligations, working capital, required utilization, expected revenue or gross contribution, operating cost, downtime reserve, driver requirement, insurance effect, customer demand and marginal cash contribution. Does the next truck create profit—or merely create fleet size? Do not recommend an added rig merely because its equipment can be acquired.
Demand governs scale. Use contracted and expected loads, customer concentration, loaded-mile demand, utilization, available drivers, terminal and loading capacity, dispatch capacity, insurance, lease availability and compliant equipment. A driver shortage, weak demand, constrained terminal or insufficient cash can cap supported active units below the equipment budget.
Fleet Capacity Multiplier = permanent capital required per conventional active unit ÷ permanent capital required per hybrid active unit. Active Unit Multiplier = supported active hybrid units ÷ supported active conventional units. A ratio with a zero or unsupported denominator is unavailable, not an invented advantage. Calculate from actual purchase, inspection, reconditioning, financing, lease, deposit and working-capital assumptions.
Show same starting capital, conventional and hybrid supported active units, permanent capital per active unit, working capital remaining, fixed monthly cash requirement and required utilization first. Then compare gross contribution per active unit, cost per total mile, loaded or revenue mile and operating day; break-even and incremental-unit utilization; marginal cash contribution; liquidity runway; three-, five- and seven-year cash requirements where useful; and supported replacement cycles and residual values. State whether the operating basis is revenue or gross contribution, and keep the cost bridge consistent.
Test the larger active fleet against lower utilization, fewer loads, customer loss, higher lease and insurance costs, delayed receivables, increased fuel float, driver shortage, tractor downtime, surprise tanker reconditioning and terminal constraints. If it cannot survive the downside, reduce scale. More trucks without economic demand are not strategic scaling.
True downtime cost
What does one unscheduled day off the road really cost the business?
True Downtime Cost = tow + repair + replacement equipment + driver idle + lost gross contribution + actual service or contract cost + management or operational disruption.
Model tractor and tanker downtime separately. Use user-supplied values or supported estimates; a zero is an explicit assumption, not evidence that an unknown cost does not exist. Do not invent missed-load revenue or contract penalties. State the lost-contribution basis and avoid counting the same repair, rental, idle-driver or operating cost again elsewhere. Fully burdened downtime can reverse an apparently cheap tractor decision and change how much active fleet the business can support.
Economics first. Tax attributes second.
Never buy a bad asset for a tax deduction. Use tax attributes to improve an already superior capital decision.
Determine the best pre-tax operating architecture first. After-tax cash flow and deduction timing remain conditional on explicitly supported, current tax assumptions: entity and taxpayer, tax basis, placed-in-service timing, business use, applicable limitations and professionally reviewed depreciation or lease-deduction treatment. No default Section 179 amount, bonus-depreciation percentage, depreciation life or entity treatment is assumed here. A deduction does not make equipment free. Professional tax review is required for the actual transaction; when treatment is unsupported, the after-tax comparison remains unavailable.
Optional reserve capacity: a secondary advanced optimization
Only after the active fleet architecture has been solved, compare E: optional reserve capacity. An operator may own more specialized tankers than active tractors and activate additional horsepower when supported demand arrives. This can have value when acquisition prices, future demand, lease availability and equipment lead times justify it. It is an extension of active scaling, not the primary strategy.
Choose reserve quantities explicitly and carry their storage, inspection, insurance, certification, maintenance, deterioration, capital commitment and opportunity costs. Preserve equipment condition and test whether later activation can obtain drivers, terminal capacity, insurance, compliant equipment, customer contracts and working capital. Distinguish supported active rigs from optional unactivated tanker capacity; extra parked equipment does not increase the active-unit result.
Illustrative decision framework. Not a GCP client project, performance record, equipment reliability promise or individualized acquisition, financing or tax recommendation. Results depend on the visitor’s assumptions, actual equipment condition, available contracts and professional review.
One Enterprise. Three Lenses. One Coordinated View.
Corporate cash, commodity exposure, currency, sourcing, financing, working capital, acquisitions and operations are linked. Golden Capital Partners can evaluate those connections across Business Consulting, Investment Advisory, and Markets & Risk while each service remains governed by its proper mandate.
Integrated Thinking. Controlled Mandates.
Business Consulting
What should the enterprise do? Strategy, sourcing, contracts, capital allocation, financing architecture, acquisitions, expansion, enterprise value, scenario analysis and sequencing.
Investment Advisory / RIA
What should eligible corporate investment capital be doing? Where appropriate under a separate advisory engagement: liquidity architecture, corporate investment policy, cash-equivalent and fixed-income strategy, duration, credit quality, reserve structure and investment management.
Markets & Risk / CTA
Which hedgeable market exposures should be controlled? Where appropriate under a separate CTA / risk-management engagement: commodities, energy, currency, futures/options risk architecture, hedge ratios, tenor, basis risk, roll structure and scenario protection.
Integrated Thinking. Controlled Mandates.
Business Consulting
What should the enterprise do?
Strategy, sourcing, contracts, capital allocation, financing architecture, acquisitions, expansion, enterprise value, scenario analysis and sequencing.
Investment Advisory / RIA
What should eligible corporate investment capital be doing?
Where appropriate under a separate advisory engagement: liquidity architecture, corporate investment policy, cash-equivalent and fixed-income strategy, duration, credit quality, reserve structure and investment management.
Markets & Risk / CTA
Which hedgeable market exposures should be controlled?
Where appropriate under a separate CTA / risk-management engagement: commodities, energy, currency, futures/options risk architecture, hedge ratios, tenor, basis risk, roll structure and scenario protection.
Potential scope only. Separate relevance, eligibility, conflict, mandate and agreement review; multiple service requests permitted.
Decision architecture.
- OBJECTIVE
- FACTS
- THESIS
- COUNTER-THESIS
- ECONOMICS
- CONTROL
- FAILURE CASE
- OPTIONALITY
- SEQUENCE
- KILL CRITERIA
- DECISION
- PROOF
A Strategic Asset the CEO Can Actually Use.
The value is not another report. It is having an independent strategic mind available when a consequential decision needs to be tested, sharpened, confirmed or stopped.
Who Do You Call Before You Commit?
Do not submit privileged, proprietary, trade-secret or highly sensitive information through the initial website form. Sensitive materials should be exchanged only after the appropriate engagement and information-handling process is established.